
Real Questions. Clear Answers. No Pressure.
Buying your first home comes with a lot of questions.
Some are financial.
Some are about the process.
Some are about whether you are even ready.
And some are the questions buyers are sometimes afraid to ask because they think they should already know the answer.
You are not supposed to know all of this yet.
This is your first home.
My job is to help you understand what is happening before you are asked to make major decisions.
Below are some of the questions I hear most often from first-time buyers.
DO I NEED 20% DOWN TO BUY A HOME?
No.
There are loan programs that may allow qualifying buyers to purchase with much less than 20% down.
Depending on your qualifications, you may also have access to down-payment-assistance programs.
The right amount to put down depends on your loan, available savings, monthly payment and overall financial situation.
➡️ [ READ: DOWN PAYMENT & CLOSING COSTS ]
HOW MUCH MONEY DO I ACTUALLY NEED TO BUY A HOME?
There is no single number.
You may need funds for:
Down payment
Closing costs
Earnest money
Inspection
Appraisal
Moving expenses
and:
Savings after closing
The amount depends on your purchase price, loan program, available credits and other factors.
Your down payment is not the same thing as your total cash to close.
WHAT IS CASH TO CLOSE?
Cash to close is the final amount you are expected to provide at settlement after accounting for:
Down payment.
Closing costs.
Prepaid expenses.
Earnest money already deposited.
Seller credits.
Lender credits.
Other applicable adjustments.
Your lender and closing documents will show the final amount.
WHAT IS EARNEST MONEY?
Earnest money is a deposit made after your offer is accepted according to your purchase contract.
It demonstrates that you are serious about moving forward with the transaction.
If the purchase closes, that money is generally credited within your final settlement calculation.
It is not necessarily an additional cost on top of everything else.
However, whether earnest money is refundable if you cancel depends on the contract, timing and circumstances.
DO I NEED PERFECT CREDIT?
No.
Different mortgage programs have different credit requirements.
Your credit can affect:
Qualification.
Interest rate.
Mortgage insurance.
Available programs.
But do not assume you cannot buy simply because your credit is not perfect.
Talk to a lender first.
WHAT CREDIT SCORE DO I NEED?
There is no single minimum credit score that applies to every mortgage.
Requirements vary by:
Loan program.
Lender.
Down payment.
Borrower profile.
Assistance program.
A mortgage professional should review your specific circumstances.
I HAVE STUDENT LOANS. CAN I STILL BUY?
Potentially, yes.
Student debt does not automatically prevent someone from becoming a homeowner.
The lender looks at how your qualifying debt obligations compare with your income and other financial factors.
I HAVE A CAR PAYMENT. DOES THAT MATTER?
Yes, because monthly debt payments can affect how much mortgage you qualify for.
But having a car loan does not automatically prevent you from buying.
Your lender evaluates the complete financial picture.
SHOULD I PAY OFF ALL MY DEBT BEFORE APPLYING?
Not automatically.
Sometimes reducing debt may improve mortgage qualification.
But sometimes using a large amount of savings to pay off debt could create another problem by reducing the funds you have available for closing or reserves.
Talk to your lender before making major financial moves.
HOW DO I KNOW HOW MUCH HOME I CAN AFFORD?
Start with the monthly payment that feels comfortable to you.
Then consider:
Income.
Debt.
Interest rate.
Down payment.
Property taxes.
Insurance.
HOA.
Mortgage insurance.
Other household expenses.
Your lender can estimate what purchase price corresponds with that payment.
➡️ [ READ: HOW MUCH CAN I AFFORD? ]
IF A LENDER APPROVES ME FOR $600,000, SHOULD I BUY A $600,000 HOME?
Not necessarily.
A lender determines what you may qualify to borrow.
You determine what you are comfortable spending.
There can be a big difference between the two.
SHOULD I TALK TO A REALTOR OR A LENDER FIRST?
Either conversation can be a good starting point.
I often recommend starting with a quick buyer consultation so we can talk about:
Your goals.
Timeline.
Approximate budget.
Areas of interest.
Then I can help connect you with an appropriate lender if you do not already have one.
Before seriously shopping for homes, however, you generally want to understand your financing.
WHAT HAPPENS WHEN I TALK TO A LENDER?
The lender will usually ask about:
Income.
Employment.
Monthly debts.
Savings.
Credit.
Down payment.
Home-buying timeline.
They may ask you to provide documents such as:
Pay stubs.
W-2s.
Bank statements.
Tax documents when applicable.
Identification.
Other financial records.
➡️ [ READ: MORTGAGE & FINANCING ]
WHAT IS A PRE-APPROVAL?
A pre-approval is an initial lender evaluation indicating that you may qualify for mortgage financing within certain parameters.
It helps determine:
Your potential purchase range.
Possible loan options.
Estimated payment.
It can also make your offer stronger when you are ready to purchase.
A pre-approval is not a final loan guarantee.
DOES GETTING PRE-APPROVED HURT MY CREDIT?
It depends on how and when the lender checks your credit.
Ask:
“Will this be a soft inquiry or hard inquiry?”
and:
“At what point will you pull my credit?”
Your lender should explain their process.
WHAT IS DTI?
DTI means:
DEBT-TO-INCOME RATIO
It compares qualifying monthly debt obligations with qualifying monthly income.
Lenders use it as one part of mortgage qualification.
Different programs and borrowers can have different allowable ratios.
WHAT IS PMI?
PMI stands for:
PRIVATE MORTGAGE INSURANCE
It may apply to certain conventional mortgages when the buyer makes a smaller down payment.
Mortgage insurance primarily protects the lender if the borrower defaults.
Your lender can explain whether your loan requires it and how much it costs.
WHAT IS FHA?
FHA financing is a mortgage option insured by the Federal Housing Administration.
It can be useful for some first-time buyers because its qualification structure differs from conventional financing.
FHA loans also include mortgage-insurance requirements.
WHAT IS A CONVENTIONAL LOAN?
A conventional mortgage is not insured by FHA or guaranteed by VA.
There are different conventional loan programs with different qualification and down-payment requirements.
WHAT IS A VA LOAN?
VA loans are available to eligible veterans, active-duty service members and certain other qualified borrowers.
They can offer valuable financing benefits.
Eligibility and qualification should be reviewed with a lender experienced in VA financing.
WHAT IS DOWN PAYMENT ASSISTANCE?
Down-payment assistance, or DPA, is financial assistance available through certain programs to qualifying buyers.
It may help with:
Down payment.
Closing costs.
Or both.
Programs can be structured differently.
Some are forgivable.
Some are repayable.
Some are second mortgages.
Some are grants.
Never assume assistance is free money.
➡️ [ READ: DOWN PAYMENT ASSISTANCE ]
ARE THERE FIRST-TIME BUYER PROGRAMS IN NEVADA?
Yes.
There are state and local programs that may be available to qualifying Southern Nevada buyers.
Program eligibility can depend on:
Income.
Credit.
Purchase price.
Occupation.
First-time-buyer status.
Funding availability.
Other requirements.
Ask a lender familiar with Nevada assistance programs to compare your options.
WHAT DOES “FIRST-TIME HOME BUYER” MEAN?
It does not always mean you have never owned a home before.
Some programs consider someone a first-time buyer if they have not owned a home during a particular period, such as the previous three years.
Program definitions vary.
CAN MY FAMILY HELP WITH MY DOWN PAYMENT?
Potentially.
Certain mortgage programs allow eligible gift funds.
The lender may require documentation showing where the funds came from and that they meet program rules.
Do not move large amounts of money into your account without first talking to your lender.
SHOULD I EMPTY MY SAVINGS ACCOUNT TO PUT MORE MONEY DOWN?
Usually, I would want you to think carefully before doing that.
A larger down payment can reduce the mortgage amount.
But after closing, you may still need money for:
Moving.
Repairs.
Furniture.
Insurance deductibles.
Maintenance.
Emergencies.
Owning a home should not leave you financially terrified every month.
IS RENTING ALWAYS A WASTE OF MONEY?
No.
Renting provides housing and flexibility.
It may make sense if:
You expect to move soon.
Your job situation is uncertain.
You need more time to save.
You are not ready for maintenance responsibilities.
Buying and renting both have costs.
The goal is not to buy simply because someone told you renting is bad.
The goal is to determine what fits your life.
WHAT IS EQUITY?
Equity is the difference between:
The home’s market value.
and:
What you still owe on it.
For example:
Home value:
$500,000
Mortgage balance:
$400,000
Approximate equity:
$100,000
Equity can potentially grow as you pay down your mortgage and if the home’s value increases.
Home values can also decline.
DOES MY ENTIRE MORTGAGE PAYMENT BUILD EQUITY?
No.
Your payment may include:
Principal.
Interest.
Taxes.
Insurance.
Mortgage insurance.
Only the principal portion directly reduces your loan balance.
IS BUYING ALWAYS BETTER THAN RENTING?
No.
Homeownership can provide:
Potential equity.
More control over your property.
Long-term housing stability.
But it also comes with:
Maintenance.
Repairs.
Taxes.
Insurance.
Transaction costs.
Less flexibility.
The right answer depends on you.
HOW LONG SHOULD I PLAN TO STAY IN THE HOME?
There is no universal number.
But buying can be less attractive if you expect to move again very quickly because buying and selling both involve costs.
Think about:
Your career.
Family.
Relocation plans.
Lifestyle.
Long-term goals.
HOW DO I CHOOSE A NEIGHBORHOOD?
Start with objective factors that matter to your life.
For example:
Commute.
Budget.
Home type.
Community amenities.
HOA.
Lot size.
Access to shopping.
Access to parks.
Distance from family or work.
Future resale considerations.
If school zoning matters to you, verify current information directly through the Clark County School District.
SHOULD I BUY THE BIGGEST HOUSE I CAN AFFORD?
Not necessarily.
A larger home may also mean:
Higher mortgage.
Higher utilities.
Higher maintenance.
More furniture.
More repairs.
Higher insurance.
Your first home does not need to be your forever home.
WHAT IF MY FIRST HOME ISN’T PERFECT?
That’s okay.
Most buyers make compromises.
I usually encourage first-time buyers to separate:
MUST-HAVES
from:
NICE-TO-HAVES.
Location, functionality and overall financial fit often matter more than cosmetic perfection.
WHAT IS AN HOA?
HOA stands for:
HOMEOWNERS ASSOCIATION
An HOA may establish community rules and collect regular assessments.
Before buying in an HOA community, you should review important documents involving:
Fees.
Rules.
Parking.
Pets.
Rental restrictions.
Financial condition.
Insurance.
Potential assessments.
Do not look only at the monthly fee.
WHAT IS AN INSPECTION?
A home inspection helps you understand the property’s physical condition.
The inspector may evaluate accessible areas involving:
Roof.
HVAC.
Electrical.
Plumbing.
Structure.
Appliances.
Exterior.
Other systems.
The inspection is primarily for your information as the buyer.
➡️ [ READ: INSPECTIONS & APPRAISALS ]
DOES A HOME PASS OR FAIL INSPECTION?
Usually, no.
A standard home inspection is not simply a pass-or-fail test.
The inspector documents findings.
You then evaluate which items are:
Major.
Safety-related.
Maintenance.
Minor.
DOES THE SELLER HAVE TO FIX EVERYTHING THE INSPECTOR FINDS?
No.
Whether repairs are completed depends on:
Your contract.
Negotiations.
The seller.
The issue.
The market.
The seller may agree, refuse or propose another solution.
WHAT IS AN APPRAISAL?
An appraisal is an independent professional opinion of the home’s value used during many financed purchases.
The lender generally orders it.
The appraisal helps the lender determine whether the property’s value reasonably supports the mortgage transaction.
WHAT HAPPENS IF THE APPRAISAL IS LOWER THAN MY OFFER?
Example:
Purchase price:
$500,000
Appraisal:
$485,000
That creates a:
$15,000 appraisal gap.
Possible options may include:
Seller reducing price.
Buyer contributing more funds.
Renegotiation.
Reviewing the appraisal.
Using contractual protections if applicable.
What happens depends on your contract and financing.
DOES A LOW APPRAISAL MEAN THE DEAL IS DEAD?
No.
It means we need to evaluate the options.
WHAT IS A SELLER CREDIT?
A seller credit is money the seller agrees to contribute toward eligible buyer closing expenses.
For example:
$10,000 seller credit
may potentially reduce the amount of eligible closing costs you need to pay yourself.
Seller-credit limits and permitted uses depend on your loan and transaction.
IS A SELLER CREDIT THE SAME AS A PRICE REDUCTION?
No.
A price reduction lowers the purchase price.
A seller credit can help reduce eligible upfront transaction costs.
Depending on the buyer, one may be more valuable than the other.
CAN I ASK THE SELLER TO PAY MY CLOSING COSTS?
You can potentially negotiate seller credits.
Whether the seller agrees and how much your loan allows depends on the transaction.
WHAT HAPPENS AFTER MY OFFER IS ACCEPTED?
This is when the transaction becomes more serious.
Typical next steps may include:
Earnest money.
Inspection.
Seller disclosures.
HOA documents if applicable.
Mortgage processing.
Appraisal.
Underwriting.
Insurance.
Final walkthrough.
Closing.
➡️ [ READ: HOME BUYING PROCESS ]
WHAT IS UNDERWRITING?
Underwriting is the lender’s detailed review of your mortgage application.
They may verify:
Income.
Credit.
Employment.
Assets.
Debt.
Property.
Insurance.
Other information.
The underwriter may ask for additional documents before final approval.
WHY DOES THE LENDER KEEP ASKING ME FOR MORE DOCUMENTS?
Because mortgage documents must often be current and complete.
The lender may need:
Updated pay stubs.
New bank statements.
Additional explanation.
Missing pages.
Employment verification.
This is common.
Respond quickly.
CAN I BUY A CAR WHILE I’M BUYING A HOME?
Please talk to your lender first.
Taking on new debt can affect your mortgage qualification.
CAN I FINANCE FURNITURE BEFORE CLOSING?
Again:
Talk to your lender first.
Opening new credit or taking on additional debt before closing can create problems.
SHOULD I CHANGE JOBS WHILE I’M BUYING?
Do not make a major employment change without discussing it with your lender.
Employment and income are important parts of mortgage qualification.
WHY DO YOU SAY “KEEP YOUR FINANCES BORING”?
Because boring is beautiful during a mortgage transaction.
Avoid unnecessary:
New debt.
New credit.
Large unexplained deposits.
Large transfers.
Job changes.
Co-signing.
Get the keys first.
WHAT IS TITLE AND ESCROW?
Title and escrow professionals help coordinate important parts of the closing process.
Their work can involve:
Title review.
Handling funds.
Preparing settlement information.
Coordinating documents.
Recording ownership.
Your specific transaction determines the services involved.
WHAT IS TITLE INSURANCE?
Title insurance helps protect against certain covered title-related risks.
Your title/escrow professional can explain the policies involved in your transaction and who they protect.
WHAT IS A FINAL WALKTHROUGH?
The final walkthrough happens shortly before closing.
It is an opportunity to confirm that the property is generally in the expected condition and that agreed-upon items remain or have been addressed as required.
It is not usually a second full home inspection.
WHEN DO I ACTUALLY GET THE KEYS?
Signing documents does not always mean immediate ownership.
The transaction may still need to:
Fund.
Record.
Meet contractual possession requirements.
Once that happens, you can receive possession according to your agreement.
CAN A DEAL FALL APART AFTER MY OFFER IS ACCEPTED?
Yes.
Possible issues can involve:
Financing.
Inspection.
Appraisal.
Title.
Insurance.
Buyer financial changes.
Seller issues.
Contract disputes.
Other circumstances.
An accepted offer is a major milestone, not the finish line.
CAN I CANCEL AFTER MY OFFER IS ACCEPTED?
Potentially, depending on:
Your contract.
Your contingencies.
Your deadlines.
The reason for cancellation.
Applicable legal rights.
Do not assume you can cancel at any time without consequences.
WILL I GET MY EARNEST MONEY BACK IF I CANCEL?
Not automatically.
Whether earnest money is refundable depends on the contract and circumstances.
SHOULD I WAIVE MY INSPECTION OR APPRAISAL TO WIN A HOUSE?
That can increase your risk significantly.
Before waiving an important contractual protection, make sure you understand exactly what you are giving up.
Winning the house is not the goal.
Buying the right house on terms you understand is the goal.
WHAT IF THERE ARE MULTIPLE OFFERS?
Then we focus on writing the strongest reasonable offer that still makes sense for you.
That could involve:
Price.
Closing timeline.
Credits.
Contingencies.
Financing.
Other terms.
We do not need to “win” at any cost.
SHOULD I OFFER ABOVE ASKING PRICE?
Sometimes it can make sense.
Sometimes it doesn’t.
List price is a marketing number.
We should look at:
Comparable sales.
Competition.
Condition.
Market activity.
Your budget.
Your risk tolerance.
Then decide.
CAN I OFFER LESS THAN ASKING PRICE?
Yes.
Whether that strategy makes sense depends on the property and market circumstances.
CAN YOU NEGOTIATE FOR ME?
Yes.
Negotiation is an important part of buyer representation.
That can involve more than just price.
Depending on the transaction, we may negotiate:
Seller credits.
Repairs.
Closing timeline.
Personal property.
Other contract terms.
DO I NEED A REALTOR FOR NEW CONSTRUCTION?
You are generally free to seek buyer representation, but builder registration and compensation policies vary.
Some builders require your agent to be registered with you during your first interaction or initial model-home visit.
Contact me before visiting the builder.
➡️ [ READ: WHY USE A REALTOR FOR NEW CONSTRUCTION? ]
DOES THE BUILDER’S SALES REPRESENTATIVE REPRESENT ME?
The on-site sales team works for or on behalf of the builder or owner-developer.
Their role is to sell the builder’s homes.
A buyer’s agent can help you evaluate the purchase from your side.
ARE NEW HOMES ALWAYS BETTER THAN RESALE HOMES?
No.
New construction may offer:
New systems.
Modern layouts.
Builder warranties.
Potential incentives.
Customization.
Resale homes may offer:
Established neighborhoods.
Finished landscaping.
Existing upgrades.
Potentially larger lots.
Different pricing opportunities.
The right answer depends on your priorities.
DO BRAND-NEW HOMES NEED INSPECTIONS?
New does not automatically mean flawless.
Independent inspections may still be valuable when permitted and appropriate.
WHAT IF I’M NOT READY TO BUY TODAY?
That’s okay.
A first-time-buyer consultation does not mean you need to start making offers tomorrow.
Maybe your plan is:
3 MONTHS
6 MONTHS
12 MONTHS
The point is to understand what needs to happen next.
WHAT SHOULD I DO FIRST?
If you are starting from zero:
1. TALK TO ME.
Tell me about your goals.
2. TALK TO A LENDER.
Understand your financial options.
3. BUILD YOUR PLAN.
Know your budget, timeline and priorities.
4. THEN START SHOPPING.
Preparation first.
House hunting second.
WHAT IF I’M EMBARRASSED THAT I DON’T KNOW ANYTHING ABOUT BUYING?
Please don’t be.
You have never bought a home before.
Why would you automatically know:
What escrow means?
How an appraisal works?
What underwriting is?
How seller credits work?
How to review an inspection?
How to calculate cash to close?
That’s what your professional team is for.
WILL YOU EXPLAIN THINGS TO ME MORE THAN ONCE?
Yes.
I’d rather explain something five times than have you sign something you do not understand.
WHAT IF I THINK A HOUSE IS WRONG FOR ME?
Tell me.
You are never obligated to like a property because I showed it to you.
WILL YOU TELL ME IF YOU THINK A HOUSE IS A BAD IDEA?
Yes.
I may tell you:
“This concerns me.”
“I don’t like this.”
“We should investigate this further.”
“The numbers don’t make sense.”
“I think we can negotiate harder.”
or:
“I think you should consider walking away.”
Good representation is not about telling you everything is wonderful.
It is about helping you see the transaction clearly.
WHY DO YOU CALL YOUR APPROACH “GOOD ENERGY”?
For me, Good Energy does not mean pretending every situation is positive.
It means approaching a major decision with:
CLARITY.
PREPARATION.
CONFIDENCE.
CALM.
My approach is:
PEACEFUL, BUT AMBITIOUS.
Peaceful enough not to panic.
Ambitious enough to negotiate and pursue opportunities.
HAVE YOU HELPED FIRST-TIME BUYERS BEFORE?
Yes.
One of my favorite buyer experiences started with a family who came to Las Vegas expecting to rent.
After connecting them with appropriate lending resources, we discovered that homeownership could actually be possible.
They ultimately purchased a home using down-payment assistance, and I negotiated:
$15,500 IN SELLER CREDITS
in that particular transaction.
They came looking for a rental.
They left with keys to a home of their own.
Every buyer and transaction is different, and no particular financing or negotiation result is guaranteed.
But that experience is a big reason I believe in helping buyers understand what may be possible before assuming they cannot own.
WHAT IS THE MOST IMPORTANT ADVICE YOU WOULD GIVE A FIRST-TIME BUYER?
DO NOT MAKE A HALF-MILLION-DOLLAR DECISION OUT OF FEAR.
Don’t buy because you’re afraid prices will rise.
Don’t walk away from a good opportunity because you’re afraid of the process.
Don’t spend your maximum approval because you’re afraid of losing a house.
Don’t skip important due diligence because you’re afraid another buyer will win.
Get the information.
Understand the numbers.
Ask the questions.
Then decide.
WHAT IF I STILL DON’T KNOW WHETHER I’M READY?
That’s exactly what the first conversation is for.
You don’t need:
A property picked out.
A pre-approval already completed.
Perfect credit.
20% down.
Every answer.
You just need to tell me where you are today.
Then we figure out the next step.
READY TO ASK YOUR OWN QUESTIONS?
If your question wasn’t answered here, ask it.
There are no embarrassing first-time-buyer questions.
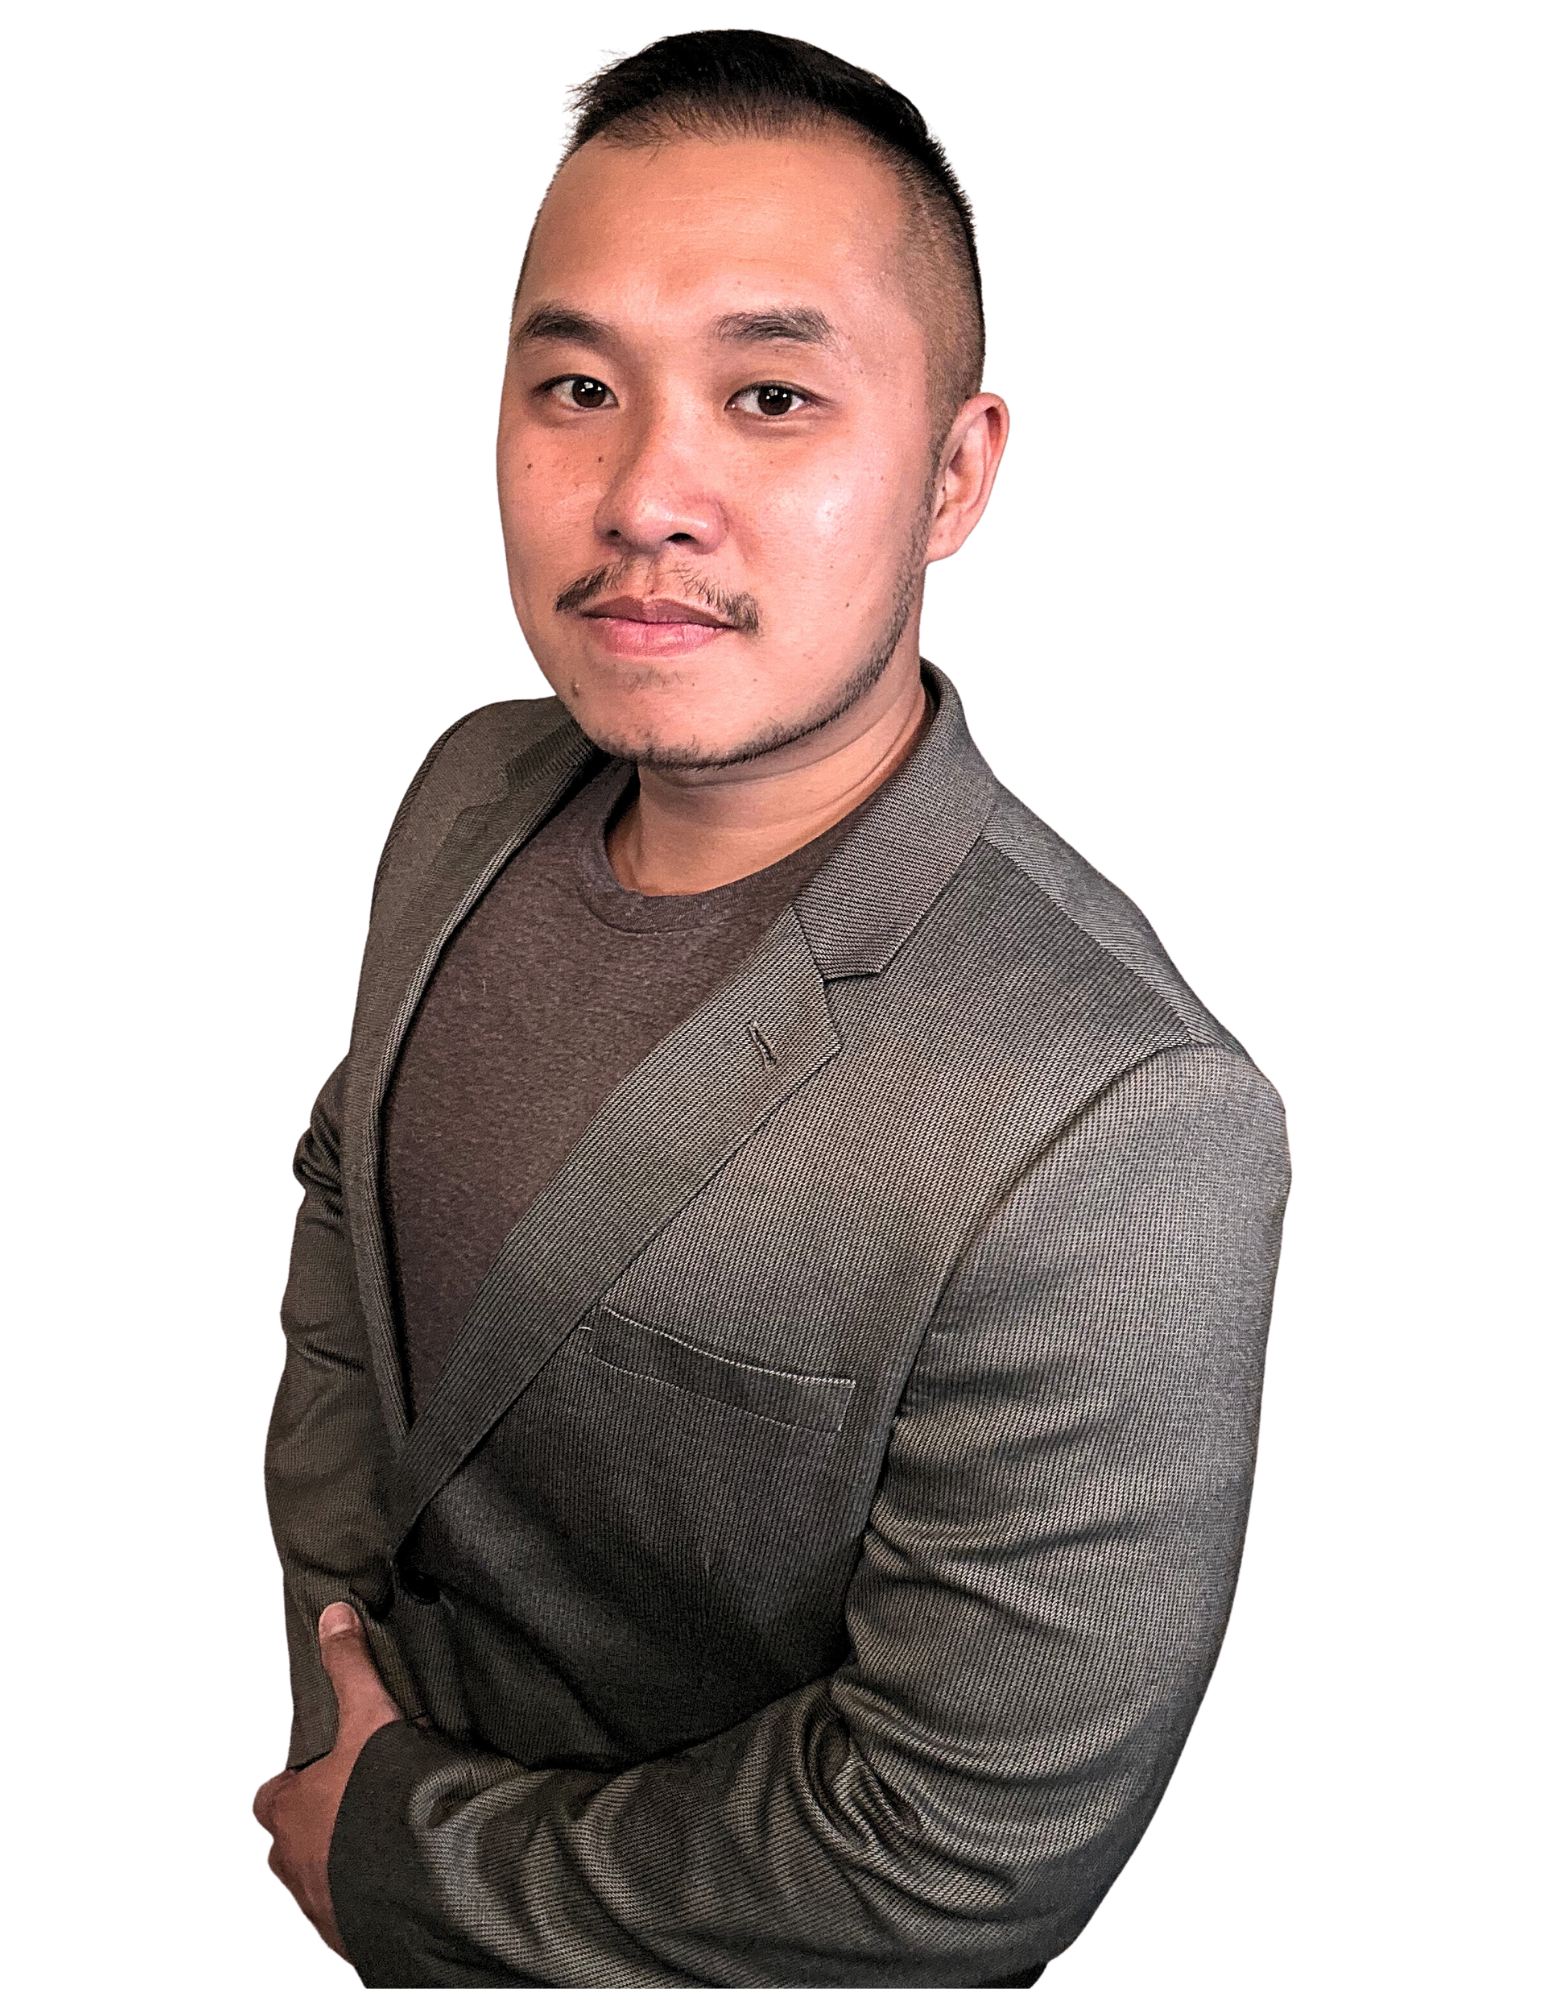
TOMMY XAVIER NGUYEN
The Good Energy Realtor®
Nevada Real Estate Salesperson
NV Lic. #S.0204577
Good Energy Realty LLC
📞 725.224.1720
Serving:
Las Vegas • Henderson • North Las Vegas • Boulder City • Southern Nevada
Calm questions. Clear answers. Strong decisions.
[ BUTTON: ASK TOMMY A QUESTION ]
[ BUTTON: START MY FIRST-HOME PLAN ]
[ BUTTON: FIRST-TIME BUYER GUIDE ]
CONTINUE LEARNING
FIRST-TIME HOME BUYER GUIDE
Start with the complete beginner’s guide.
[ READ THE GUIDE → ]
DOWN PAYMENT ASSISTANCE
Explore programs that may help qualifying Southern Nevada first-time buyers.
[ EXPLORE DPA OPTIONS → ]
MORTGAGE & FINANCING
Learn what lenders look for and what to expect during pre-approval.
[ LEARN ABOUT MORTGAGES → ]
DOWN PAYMENT & CLOSING COSTS
Understand how much money you may actually need.
[ UNDERSTAND THE COSTS → ]
INSPECTIONS & APPRAISALS
Learn the difference between evaluating a home’s condition and its value.
[ LEARN MORE → ]
HOME BUYING PROCESS
Ready for the complete step-by-step transaction?
[ VIEW THE PROCESS → ]
IMPORTANT INFORMATION
This FAQ is intended for general home-buyer education.
Every purchase contract, mortgage, property and buyer situation is different.
Financing requirements, assistance programs, inspection rights, appraisal protections, seller contributions, deadlines and other transaction terms can vary and may change.
The Good Energy Realtor® and Good Energy Realty LLC do not provide mortgage, legal, tax, inspection or financial advice.
Consult the appropriate licensed professional for advice specific to your transaction.